
ASX NEWS | ECONOMICS & INTERNATIONAL AFFAIRS | NOVEMBER 13, 2026
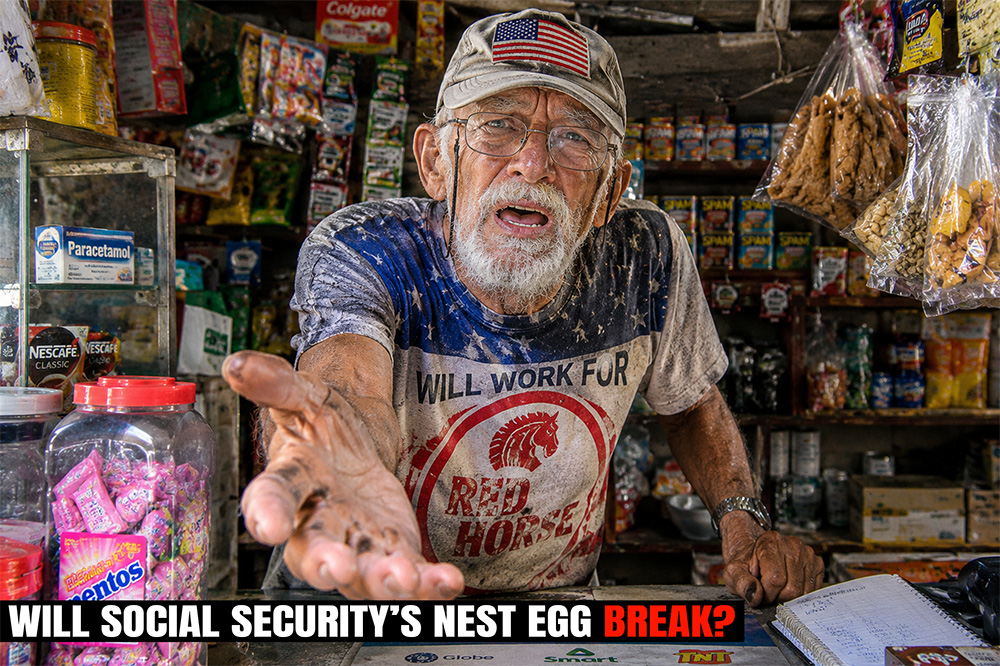
For thousands of American retirees who have exchanged the rising cost of living in the United States for the tropical climate, affordable housing, and comparatively lower everyday expenses of the Philippines, a financial storm gathering in Washington could threaten the very foundation of their retirement.
The United States Social Security system, long regarded as one of the most dependable pillars of American retirement security, is approaching a critical funding deadline. According to the 2026 Social Security Trustees Report, the trust fund responsible for paying retirement and survivor benefits is projected to exhaust its reserves in the fourth quarter of 2032. Without congressional intervention, incoming revenue would be sufficient to cover only 78 percent of scheduled benefits.
For American retirees living in the Philippines, the implications extend far beyond a smaller monthly deposit. A potential 22 percent reduction in Social Security benefits could undermine carefully constructed retirement budgets, compromise access to healthcare, erode emergency savings, and force some expatriates to reconsider whether they can afford to remain overseas.
For those who have spent decades working, paying into the system, and planning their retirement around the expectation of financial stability, the prospect is deeply unsettling.
And for Americans who have already established permanent lives in the Philippines, the consequences of Washington’s failure to address the crisis could be particularly severe.
America’s Retirement System Is Approaching a Financial Crossroads
The latest projections from the Social Security Administration paint a troubling picture of the program’s long-term financial position.
The Old-Age and Survivors Insurance (OASI) Trust Fund, which finances retirement and survivor benefits, is projected to deplete its reserves in late 2032. At that point, continuing revenue would cover approximately 78 percent of scheduled benefits.
When the retirement and disability trust funds are considered together, their combined reserves are projected to last until 2034, after which approximately 83 percent of scheduled benefits could be financed through continuing revenue.
However, the two funds are legally separate. The combined projection should not be interpreted as an automatic extension of the retirement fund’s solvency until 2034.
The distinction is important: for retirees receiving conventional Social Security retirement benefits, 2032 represents the more immediate funding deadline under current projections.
Trust fund depletion does not mean Social Security will disappear. American workers and employers will continue paying payroll taxes, providing a substantial revenue stream. The problem is that the system would no longer possess sufficient reserves and incoming revenue to finance every scheduled payment in full.
Congress would therefore need to enact changes to the program’s financing, benefits, or both to prevent a significant disruption.
As of November 2026, no across-the-board 22 percent reduction has been enacted. The projected shortfall is a warning about what could happen under existing law if policymakers fail to act, not an announcement that retirees will definitely lose a specified percentage of their checks on a particular date.
How America’s Changing Economy Accelerated the Crisis
For decades, discussions about Social Security’s financial difficulties have focused primarily on demographics. Americans are living longer, birth rates have declined, and the ratio of workers contributing to the system relative to beneficiaries receiving payments has deteriorated.
But new research published on November 10, 2026, by the AARP Public Policy Institute identifies another major contributor: the changing structure of American income.
In the early 1980s, earnings subject to Social Security payroll taxes represented approximately 41 percent of the nation’s gross domestic product. By 2025, that proportion had declined to approximately 34 percent.
The American economy has continued to grow, but an increasing share of that growth has occurred outside the income streams traditionally used to finance Social Security.
Higher-income workers have experienced substantial earnings growth above the annual taxable earnings ceiling, while business profits and investment income account for a significant portion of national income that generally falls outside Social Security payroll taxation.
In 2026, Social Security payroll taxes apply to the first $184,500 of an individual’s covered annual earnings. Income above that threshold is not subject to the Social Security portion of the payroll tax.
The AARP analysis estimates that, had taxable payroll maintained its earlier share of the economy, Social Security would have accumulated approximately $10.8 trillion in additional revenue and interest between 1984 and 2034.
Under that hypothetical historical scenario, the combined trust funds could have financed full scheduled benefits until 2059 — approximately 25 years beyond their current projected depletion date.
That finding does not mean Social Security is now expected to remain fully funded until 2059. Rather, it illustrates the magnitude of the revenue lost as the American economy evolved while the program’s financing structure failed to keep pace.
It also raises a fundamental policy question: should the financial burden of restoring Social Security fall primarily on retirees through reduced benefits, on workers through higher payroll taxes, or on additional sources of income that have historically remained outside the system?
Why the Philippines Has Become a Retirement Destination for Americans
For many Americans, retiring in the Philippines represents more than a desire to escape cold winters or experience life in Southeast Asia. It is an economic decision.
Housing, domestic transportation, personal services, and many everyday necessities can be considerably less expensive in the Philippines than in major American metropolitan areas. English is widely spoken, the country maintains longstanding cultural and historical connections with the United States, and established expatriate communities offer newcomers an accessible social environment.
From the urban centers of Metro Manila and Cebu to the coastal communities of Dumaguete, Subic, and smaller provincial towns, American retirees have established lives that might have been financially difficult to sustain in the United States.
Some have married Filipino citizens, purchased condominium units, established businesses, or become deeply integrated into local families and communities. Others have chosen the Philippines precisely because their Social Security income, supplemented by modest savings or a pension, can support a more comfortable standard of living than it could in their home country.
For these individuals, retirement abroad is not necessarily a luxury. It can be the financial strategy that makes retirement possible in the first place.
Unlike affluent expatriates with substantial investment portfolios, some retirees have limited capacity to absorb a sudden and permanent reduction in monthly income.
That is where America’s Social Security funding crisis intersects directly with the economic realities of life in the Philippines.
What a 22 Percent Reduction Could Mean in Philippine Pesos
The financial consequences become clearer when projected benefit reductions are translated into actual household income.
Consider an American retiree receiving $2,000 per month in Social Security retirement benefits. At an illustrative exchange rate of 58 Philippine pesos to the U.S. dollar, that income would provide approximately ₱116,000 per month before taxes, banking charges, insurance premiums, or other deductions.
If payable benefits were reduced by 22 percent, that same retiree would receive approximately $1,560 per month, equivalent to ₱90,480 at the same exchange rate.
The difference would be $440 per month, or ₱25,520 — a substantial loss for a household dependent on a fixed retirement income.
| Monthly Benefit | After 22% Reduction | Monthly Loss | Annual Loss |
|---|---|---|---|
| $1,200 | $936 | $264 | $3,168 |
| $1,500 | $1,170 | $330 | $3,960 |
| $2,000 | $1,560 | $440 | $5,280 |
| $2,500 | $1,950 | $550 | $6,600 |
| $3,000 | $2,340 | $660 | $7,920 |
Illustrative calculations based on a uniform 22 percent reduction in scheduled benefits. Actual future payments would depend on legislation, benefit adjustments, individual circumstances, and exchange rates.
For the retiree receiving $2,000 per month, the annual loss would amount to $5,280, or approximately ₱306,240 at the illustrative exchange rate.
That amount could represent a substantial portion of an annual housing budget, private medical insurance premiums, emergency savings, or financial support provided to family members.
For expatriates whose monthly income is already close to their essential living expenses, the consequences could be considerably more serious than simply reducing discretionary spending.
The Currency Trap: When a Smaller Check Meets a Stronger Peso
American retirees living in the United States generally receive and spend their Social Security benefits in the same currency. American expatriates living in the Philippines face an additional financial variable: the exchange rate between the U.S. dollar and the Philippine peso.
Social Security benefits are calculated in U.S. dollars. The Social Security Administration does not increase or decrease a beneficiary’s dollar-denominated entitlement to compensate for fluctuations in foreign exchange rates.
Consequently, a retiree can experience a meaningful change in local purchasing power even when the amount of their monthly Social Security payment remains unchanged.
When the dollar strengthens against the peso, American retirees generally benefit from increased local purchasing power. When the dollar weakens, the same monthly benefit purchases fewer Philippine pesos.
A future reduction in Social Security benefits could therefore coincide with unfavorable currency movements, creating a compounded financial shock.
Consider again the hypothetical retiree receiving $2,000 per month. At an exchange rate of ₱58 to the dollar, that income is worth ₱116,000.
Now assume benefits are reduced by 22 percent and the dollar subsequently weakens to ₱50. The retiree’s $1,560 monthly payment would convert to only ₱78,000.
Compared with the original ₱116,000, that represents a decline in local-currency income of approximately 32.8 percent.
Neither the assumed exchange rate nor the timing of a future benefit reduction is a prediction. The scenario demonstrates how two independent financial risks can combine to produce a much larger reduction in purchasing power than either would create individually.
For retirees whose expenses are denominated primarily in Philippine pesos but whose income originates entirely in U.S. dollars, currency exposure is an unavoidable consideration.
Healthcare Could Become the Most Serious Concern
Perhaps the most consequential vulnerability facing American retirees in the Philippines is healthcare.
Although routine consultations, diagnostic services, and certain medical procedures can be considerably less expensive in the Philippines than in the United States, serious illness can still generate substantial expenses.
Hospitalization, intensive care, cancer treatment, cardiovascular procedures, long-term medication, and medical evacuation can impose financial demands far beyond the ordinary monthly budget of a retiree.
American expatriates also face a critical limitation that is frequently misunderstood by prospective overseas retirees: Medicare generally does not cover medical treatment outside the United States.
There are narrow exceptions, and some private insurance arrangements provide international coverage, but conventional Medicare benefits cannot ordinarily be relied upon to pay for routine treatment or hospitalization in the Philippines.
As a result, retirees may depend on private health insurance, eligible local coverage, personal savings, or direct out-of-pocket payments.
For older expatriates, obtaining comprehensive private coverage can become increasingly difficult or expensive, particularly when pre-existing medical conditions are involved.
A retiree who currently sets aside part of a Social Security payment for medical emergencies could find that financial safety margin significantly reduced following a benefit cut.
In such circumstances, the issue is no longer whether an expatriate can afford a larger apartment, frequent restaurant meals, or recreational travel. It becomes whether that individual can afford necessary medical treatment without exhausting personal savings or becoming financially dependent on family members.
The lower cost of living that originally made the Philippines attractive does not eliminate the financial risks associated with aging.
Retirement Abroad Is Not Always Reversible
One of the most overlooked aspects of expatriate retirement is the difficulty of returning home after years or decades overseas.
Many Americans living in the Philippines have sold their homes in the United States, disposed of possessions, transferred savings overseas, and established permanent family relationships in their adopted country.
Returning to America may involve considerably more than purchasing an airline ticket.
A retiree contemplating repatriation could face expensive rental deposits, transportation costs, healthcare arrangements, and the challenge of securing suitable housing in a market that may have become dramatically more expensive since their departure.
For individuals who originally moved abroad because they could not comfortably afford retirement in the United States, a reduction in Social Security benefits could create a particularly difficult predicament.
Their reduced income might no longer support their existing lifestyle in the Philippines, yet returning to the United States could be even less financially viable.
Those with Filipino spouses, dependent children, or other family responsibilities would face additional considerations. Immigration requirements, employment opportunities for family members, and the cost of relocating an entire household could make repatriation impractical.
For these retirees, the financial crisis would not simply involve choosing between two countries. It could involve confronting the possibility that neither country offers an affordable path forward without significant changes to their standard of living.
The Impact Would Extend Beyond American Retirees
The potential consequences of reduced Social Security payments would not necessarily stop with the American expatriate receiving the benefit.
Many foreign retirees in the Philippines participate directly in the local economy. They rent apartments, purchase groceries, employ household workers, use local transportation, pay for medical services, and support small businesses.
Some also provide financial assistance to Filipino spouses, children, extended family members, and other dependents.
For households in which an American retirement payment represents a major source of income, a reduction could affect education expenses, healthcare, housing, and other essential family expenditures.
Local businesses serving expatriate communities could also experience reduced discretionary spending if significant numbers of retirees simultaneously faced tighter budgets.
The scale of any broader economic effect would depend on the number of affected beneficiaries, their spending patterns, and the eventual structure of any benefit changes.
Nevertheless, the underlying relationship is clear: American retirement income does not remain confined to the United States. When beneficiaries live overseas, those payments become part of the economic activity of their adopted communities.
Washington’s decisions regarding Social Security can therefore have consequences far beyond America’s borders.
Are American Expats Being Targeted?
There is currently no evidence that American retirees living in the Philippines are being specifically targeted for Social Security benefit reductions as part of the projected trust fund shortfall.
Eligible U.S. citizens can generally continue receiving Social Security retirement benefits while residing in the Philippines, subject to the Social Security Administration’s international payment rules.
The Philippines is also among the countries where international direct deposit of Social Security benefits is available.
The funding crisis concerns the overall financial condition of the American retirement system, not the overseas residence of individual beneficiaries.
However, living abroad does not exempt American citizens from the financial consequences of changes to Social Security.
If Congress were to enact benefit reductions affecting existing retirees, or if insufficient trust fund resources resulted in reduced payable benefits, eligible Americans living in the Philippines could be affected alongside beneficiaries residing in the United States.
It is also important to distinguish Social Security retirement benefits from Supplemental Security Income (SSI), a separate needs-based federal program that generally cannot be collected during extended residence outside the United States.
American retirees should rely on official Social Security Administration guidance rather than social media rumors when evaluating their eligibility and overseas payment arrangements.
Can Washington Prevent the Crisis?
Congress has several potential avenues for addressing Social Security’s long-term financial imbalance.
Among the proposals frequently discussed are increasing or eliminating the taxable earnings ceiling, raising payroll tax rates, adjusting the taxation of certain income sources, modifying future benefit formulas, increasing the retirement age, and introducing other changes to the program’s financing.
Each approach carries economic and political consequences.
Higher payroll taxes would increase the financial burden on workers and employers. Expanding taxation of higher incomes could generate additional revenue but would require decisions about the treatment of earnings and future benefit entitlements. Raising the retirement age would effectively reduce lifetime benefits for affected workers, while changes to benefit formulas could redistribute the impact across different income groups and generations.
Congress could also adopt a combination of measures rather than relying on a single policy change.
The new AARP research adds an important dimension to this debate by demonstrating that demographic pressures alone do not explain the program’s deteriorating finances. Changes in the distribution and composition of American income have also contributed substantially to the problem.
Social Security has faced major financing challenges before. In 1983, Congress enacted significant reforms that strengthened the program through a combination of revenue increases and benefit-related adjustments.
That historical precedent demonstrates that legislative intervention is possible. It does not, however, guarantee that today’s political leaders will reach an agreement before the projected depletion deadline.
The longer Congress delays, the less time workers, employers, and retirees will have to prepare for whatever changes ultimately become necessary.
What American Retirees in the Philippines Can Do Now
Although the projected funding shortfall remains several years away, expatriates do not need to wait until 2032 to assess their financial exposure.
A useful starting point is to examine whether essential household expenses could still be covered if Social Security income declined by 20 to 25 percent.
That exercise should include housing, utilities, food, transportation, medical expenses, insurance, immigration-related costs, and any financial obligations to dependents.
Retirees should also consider how their budgets would respond to unfavorable currency movements, particularly if the dollar were to weaken substantially against the Philippine peso.
Where financially feasible, maintaining an emergency reserve separate from ordinary monthly spending could provide additional protection against benefit changes, exchange-rate volatility, or unexpected medical expenses.
Individuals relying on a single source of retirement income may also benefit from reviewing other available resources, including pensions, savings, investment income, and appropriate employment opportunities where legally permitted.
Healthcare arrangements deserve particular attention. Retirees should understand exactly what their insurance covers in the Philippines, what exclusions apply, and how they would finance treatment that falls outside their coverage.
For those considering retirement in the Philippines in the coming years, the projected Social Security shortfall should be incorporated into long-term planning before committing to major financial decisions.
None of these precautions requires assuming that Congress will fail to protect benefits. They simply recognize that financial resilience becomes increasingly important when a household depends heavily on an income source whose future funding is uncertain.
The Larger Question: Can America Keep Its Promise to Retirees?
Social Security is more than a government payment program. For generations of Americans, it has represented an expectation that decades of employment and mandatory contributions would provide a measure of financial security in old age.
That expectation has influenced decisions about when to retire, where to live, whether to continue working, and how much money individuals believe they need to accumulate before leaving the workforce.
For American expatriates in the Philippines, those decisions have often involved crossing oceans, establishing new families, and building lives thousands of miles from the country where their retirement benefits were earned.
Many did not move overseas because they possessed enormous financial resources. They moved because the purchasing power of their retirement income offered them an opportunity to live with greater dignity, independence, and financial security.
A significant reduction in Social Security benefits could threaten that opportunity.
The Philippines would remain an attractive retirement destination for many Americans, and its comparatively lower living costs could continue to provide an important financial advantage. But affordability is relative. A lower cost of living cannot indefinitely compensate for declining income, rising medical expenses, and adverse currency movements.
Ultimately, the Social Security funding crisis is not merely a debate over actuarial projections, tax policy, or federal budget calculations. It is a question about the financial commitments America has made to its citizens — including those who now live beyond its borders.
For American retirees watching developments from Manila, Cebu, Dumaguete, or the countless smaller communities they now call home, the outcome of that debate could determine whether the retirement they worked a lifetime to achieve remains financially sustainable.
The deadline is approaching. The financial warning signs are unmistakable. And while Congress still has time to prevent a crisis, millions of Americans cannot afford to discover what happens if Washington waits too long.
The American dream does not end at America’s borders. Neither should the financial security promised to those who spent their working lives earning it.
Sources and Further Reading
Social Security Administration. 2026 Annual Report of the Board of Trustees of the Federal Old-Age and Survivors Insurance and Federal Disability Insurance Trust Funds — Highlights. June 2026.
Social Security Administration. 2026 Social Security Trustees Report — Conclusion.
Johnson, Richard W. Shifting Income Patterns Have Shortened the Life of Social Security’s Trust Fund by 25 Years. AARP Public Policy Institute, November 10, 2026.
AARP. New AARP Research Finds Social Security Revenue Depleted Due to Major Economic Changes. November 11, 2026.
Social Security Administration. Social Security Payments Outside the United States.
Social Security Administration. Your Payments While You Are Outside the United States.
Social Security Administration. International Direct Deposit — Participating Countries.
Centers for Medicare & Medicaid Services. Medicare Coverage Outside the United States.
ASX News provides independent reporting and analysis on international affairs, economics, aviation, science, and emerging technology. The financial scenarios presented in this article are illustrative and do not constitute individualized financial, legal, or retirement planning advice.